How to Create a Personal Budget That Actually Works
Sarah
Senior Reporter

Creating a personal budget sounds simple: write down your income, list your expenses, and make sure you do not spend more than you earn.
But in reality, many people create budgets that look good on paper and fail within a few weeks.
The problem is usually not the idea of budgeting. The problem is creating a budget that does not reflect how you actually live.
A good personal budget should help you understand where your money is going, control unnecessary spending, prepare for emergencies, and make progress toward your financial goals without making you feel like you cannot enjoy your income. Whether you are a student, salaried worker, entrepreneur, freelancer, or young professional in Ghana, here is how to create a personal budget that can actually work.
What Is a Personal Budget?
A personal budget is a plan for how you intend to use your income over a specific period, usually a month. It gives every major portion of your income a purpose. For example, your income may need to cover:
Rent or accommodation Food Transportation Electricity and water Internet and phone bills Family support Debt payments Savings Investments Entertainment Emergency expenses
The purpose of a budget is not to stop you from spending money. It is to make sure your spending reflects your priorities.
Step 1: Know Exactly How Much You Make
Before creating a budget, determine your actual monthly income. If you earn a salary, use the amount that reaches your account after taxes, pensions, and other deductions rather than your gross salary. If you are self-employed, a freelancer, content creator, trader, or business owner, your income may change from month to month. In that case, avoid building your lifestyle around your highest-income month. Instead, calculate your average income from the past few months and create a conservative budget based on an amount you can reasonably expect.
For example, if your monthly income has been: January: GH₵5,000 February: GH₵4,200 March: GH₵5,500 April: GH₵4,800
You could use an average or a conservative figure rather than assuming you will always make GH₵5,500. This makes your budget more realistic.
Step 2: Track Where Your Money Is Going
One of the biggest mistakes people make is creating a budget without knowing their actual spending habits. For at least one month, record everything you spend. Do not only record large expenses. A GH₵500 electricity bill is important, but so are the GH₵20, GH₵30 and GH₵50 expenses that happen repeatedly throughout the month.
Track things such as: Food Transport Mobile money charges Data bundles Eating out Shopping Subscriptions Entertainment Family support Debt payments Bank charges Impulse purchases You may be surprised by how much money disappears through small, frequent expenses.
Step 3: Separate Needs From Wants
Not every expense has the same level of importance. A useful approach is to divide your expenses into three categories: needs, wants and financial goals.
Needs
These are expenses required to maintain your basic lifestyle.
Examples include: Rent Food Transportation Utilities Healthcare Basic communication Debt obligations
Wants
These are things you enjoy but could potentially live without. Examples include: Eating at restaurants Entertainment Expensive clothing Premium subscriptions Unplanned shopping Frequent outings
Financial Goals
These are expenses that improve your future financial position. Examples include:
Emergency savings Investments Retirement contributions Debt repayment above the minimum Saving toward a business Saving toward education
This distinction makes it easier to decide what should be reduced when money becomes tight.
Step 4: Give Your Money a Job
Instead of simply saying, "I will try to spend less this month," give specific amounts or percentages a purpose. Someone living in Accra may have very different transportation and housing costs from someone living in another part of Ghana. The goal is not to copy somebody else's budget. The goal is to build one around your own income and responsibilities.
Step 5: Do Not Forget Irregular Expenses
This is where many budgets fail. Some expenses do not happen every month, but they are still predictable.
Examples include: School fees Rent advances Annual insurance Vehicle maintenance Birthdays Christmas expenses Travel Medical expenses Registration fees Home repairs
Instead of waiting until these expenses arrive, divide the expected annual cost by 12 and save monthly. For example, if you expect to spend GH₵2,400 on an annual expense, you could set aside GH₵200 every month. When the bill arrives, the money is already available.
Step 6: Build an Emergency Fund
A budget without an emergency fund can easily collapse when something unexpected happens. Your emergency fund is money set aside for genuine emergencies such as losing your income, urgent medical expenses, major repairs or other unexpected financial problems. You do not necessarily need to build a large emergency fund immediately. Start with a small target. For example: GH₵1,000 → GH₵2,000 → one month of essential expenses → three months of essential expenses. The appropriate target depends on your income stability, responsibilities and circumstances. Most importantly, keep emergency money separate from money meant for everyday spending.
Step 7: Automate Your Savings
One of the easiest ways to make a budget work is to save before you start spending. If you receive your salary on the 25th of every month, do not wait until the end of the month to see what remains. By then, there may be nothing left.
Instead, decide how much you want to save and move that amount shortly after receiving your income.
For example: Income → Savings → Investments → Bills → Lifestyle spending rather than:
Income → Spending → Spending → Spending → Whatever is left goes to savings. This simple change can make a significant difference over time.
Step 8: Budget for Fun
A budget that leaves no room for enjoyment may be difficult to maintain. You are not a machine. If every cedi is allocated to bills, savings and investments, you may eventually become frustrated and abandon the budget completely.
Set aside some money for things you enjoy. It could be GH₵100, GH₵200 or whatever amount makes sense for your income. The important thing is that entertainment should be planned rather than allowed to consume money meant for important financial goals.
Step 9: Be Careful With Lifestyle Inflation
One of the biggest challenges that comes with earning more money is lifestyle inflation. You get a salary increase, a new job or a profitable side hustle and immediately increase your expenses.
A better approach is to allow your lifestyle to improve gradually while directing part of the additional income toward your financial goals.
For example, if your income increases by GH₵1,000, you do not necessarily need to spend the entire GH₵1,000. You could allocate part of it to: Investments Emergency savings Debt repayment A future business Education Better housing or transportation Increasing your income is important, but controlling what happens to the additional income is equally important.
Step 10: Review Your Budget Every Month
A budget is not something you create once and never touch again. Your circumstances will change. Your rent may increase. Transportation costs may change. Your income may increase or decrease. You may acquire new responsibilities.
Set aside time at the end of every month to review your budget. Ask yourself: What did I spend more on than expected? Where did I spend less? Which expenses were unnecessary? Did I save what I planned to save? Did I make progress toward my financial goals? What should I change next month? This turns budgeting into a continuous process rather than a one-time exercise.
What If Your Income Is Too Small?
Sometimes the problem is not poor budgeting. Your income may simply be insufficient for your current responsibilities. If your essential expenses already consume most or all of your income, cutting small expenses may not solve the bigger problem. In that situation, your strategy may need two parts: Control expenses + increase income. You could consider developing a skill, taking on freelance work, starting a small side business, negotiating your salary where appropriate, or finding additional sources of income. A budget can show you where the problem is, but it cannot magically create money that does not exist.
Should You Follow the 50/30/20 Rule?
You may have heard of the 50/30/20 budgeting rule, where 50% of income goes toward needs, 30% toward wants and 20% toward savings and debt repayment.
It can be a useful starting point, but it should not be treated as a universal rule. Someone earning GH₵3,000 and someone earning GH₵30,000 may have completely different financial circumstances. Housing costs, family responsibilities, debt, location and financial goals can all affect the appropriate allocation. Use budgeting frameworks as guides, not as laws.
Your budget should fit your life. A Simple Monthly Budget Template If you are starting from scratch, you can use this basic structure:
Monthly income: GH₵________ Essential Expenses Rent: GH₵________ Food: GH₵________ Transport: GH₵________ Utilities: GH₵________ Phone/data: GH₵________ Healthcare: GH₵________ Family res: GH₵________
Financial Goals Emergency fund: GH₵________ Savings: GH₵________ Investments: GH₵________ Debt repayment: GH₵________
Lifestyle
Entertainment: GH₵________ Shopping: GH₵________ Eating out: GH₵________ Other personal expenses: GH₵________
Buffer
Unexpected expenses: GH₵________ Total planned spending:GH₵________ Money remaining:GH₵________
If the numbers do not balance, do not simply ignore the difference. Find out where the money is going and make adjustments. The Most Important Rule: Make Your Budget Realistic A budget does not need to be perfect. It needs to be realistic enough that you can follow it consistently.
If you normally spend GH₵500 on food and suddenly decide your new budget will allow only GH₵150, you may follow the plan for a few days and then abandon it. A better approach may be to reduce the amount gradually while looking for ways to lower your actual costs.
The same applies to saving. If saving GH₵1,000 every month is impossible, start with GH₵100 or GH₵200. Consistency matters.
Final Thoughts
Personal budgeting is not about becoming obsessed with every cedi you spend. It is about becoming intentional with your money. When you know how much you earn, understand where your money goes, plan for irregular expenses, save consistently and leave room for realistic spending, you give yourself a much better chance of achieving your financial goals.
The perfect budget does not exist. The budget that you can actually follow, review and improve every month is the one that matters. Your money should not simply disappear at the end of every month. You should know where it went and why.
Written by
Sarah
Serah is a committed reporter who is keen on accurate delivering, timely, and impactful news. Passionate about uncovering the facts, telling meaningful stories, and keeping the public informed with integrity and professionalism.
Related Stories
COCOBOD SECURES GH¢3.396BN IN LOCAL FUNDING DRIVE
Ghana's cocoa financing effort has brought in GH¢3.396 billion from local institutional investors, providing the Ghana Cocoa Board (COCOBOD) with fresh funds...
How to Save Money on a Low Income in Ghana
Saving money can feel almost impossible when your income is barely enough to cover your daily needs. For many people in Ghana, the problem is not that they do...
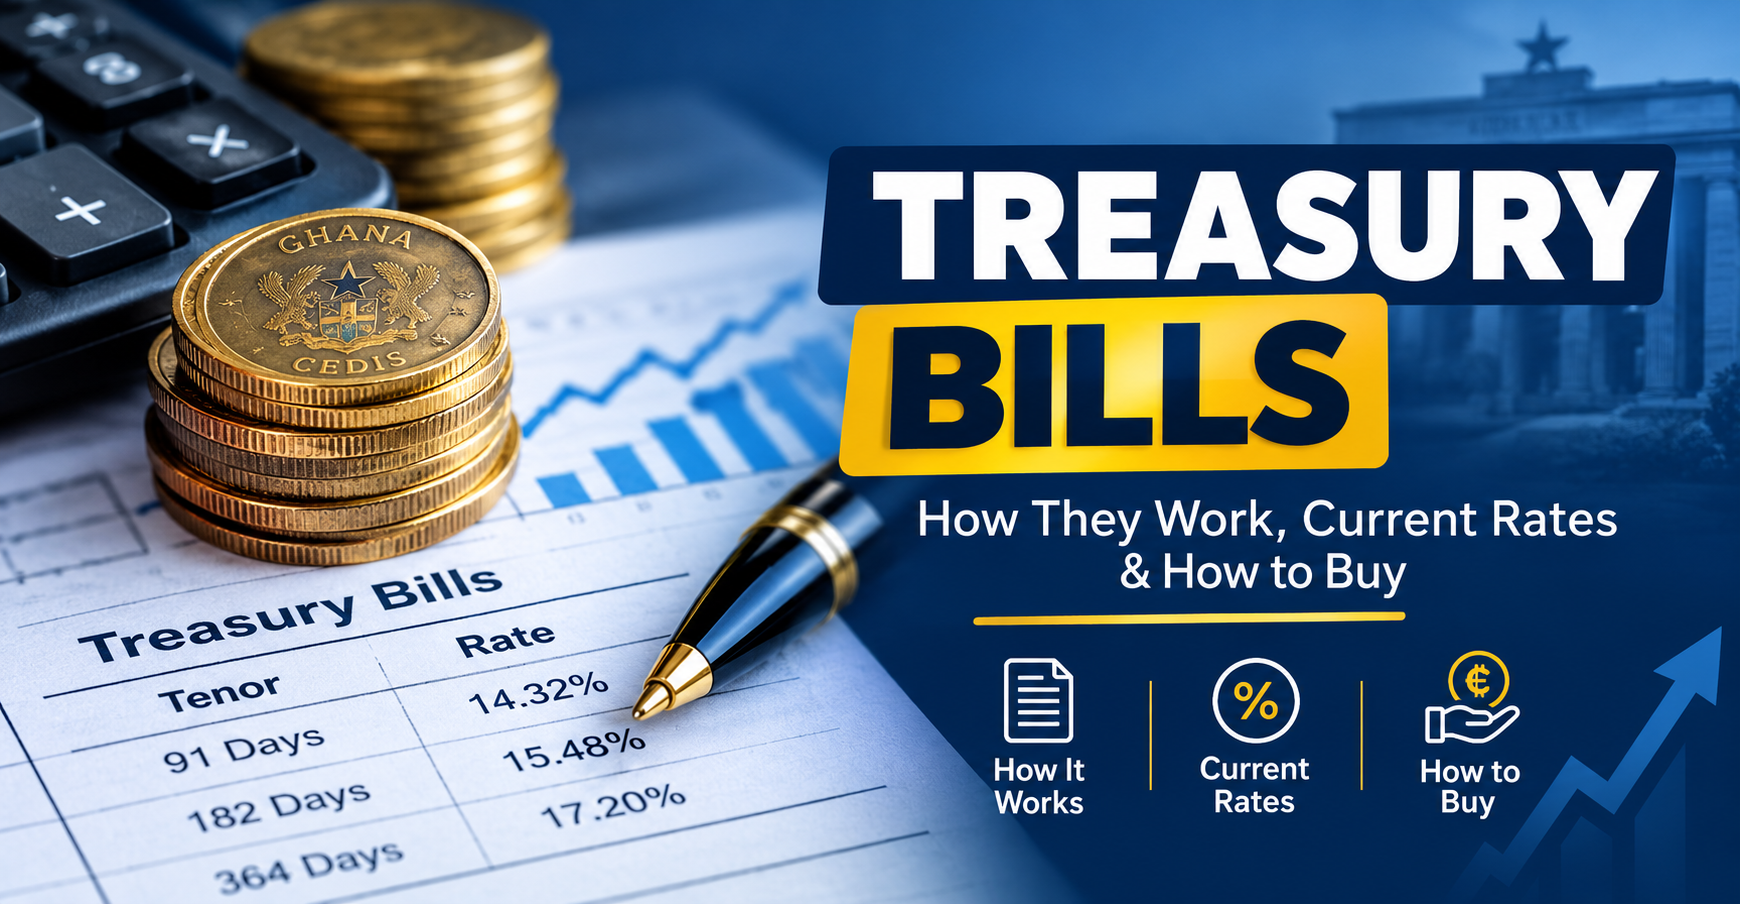
Ghana Treasury Bills: How They Work, Current Rates & How to Buy in Ghana
If you are looking for a relatively simple way to invest your money in Ghana while earning a return over a short period, Treasury Bills (T-Bills) are one of...
Comments (0)
No comments yet. Be the first to share your thoughts.